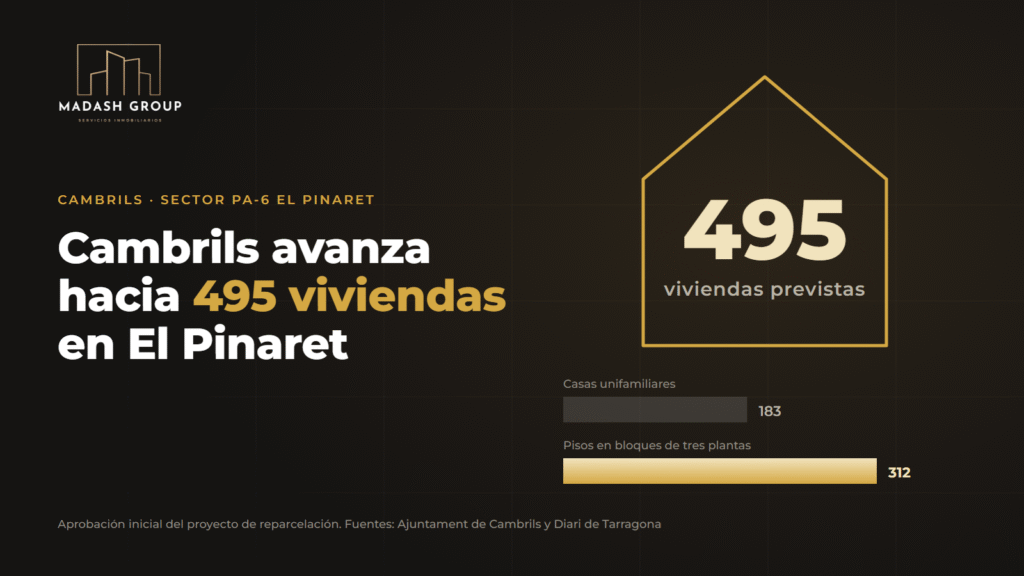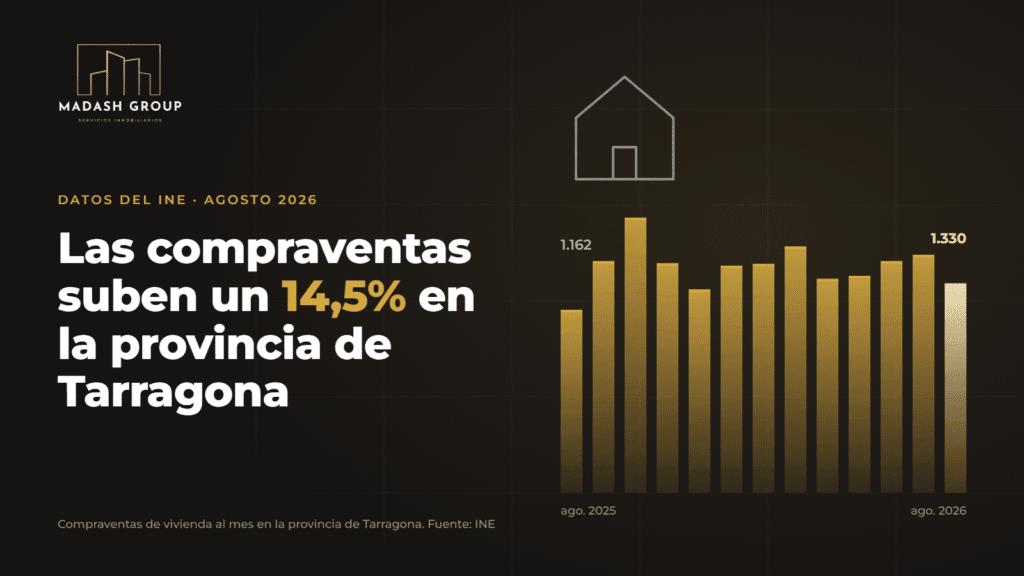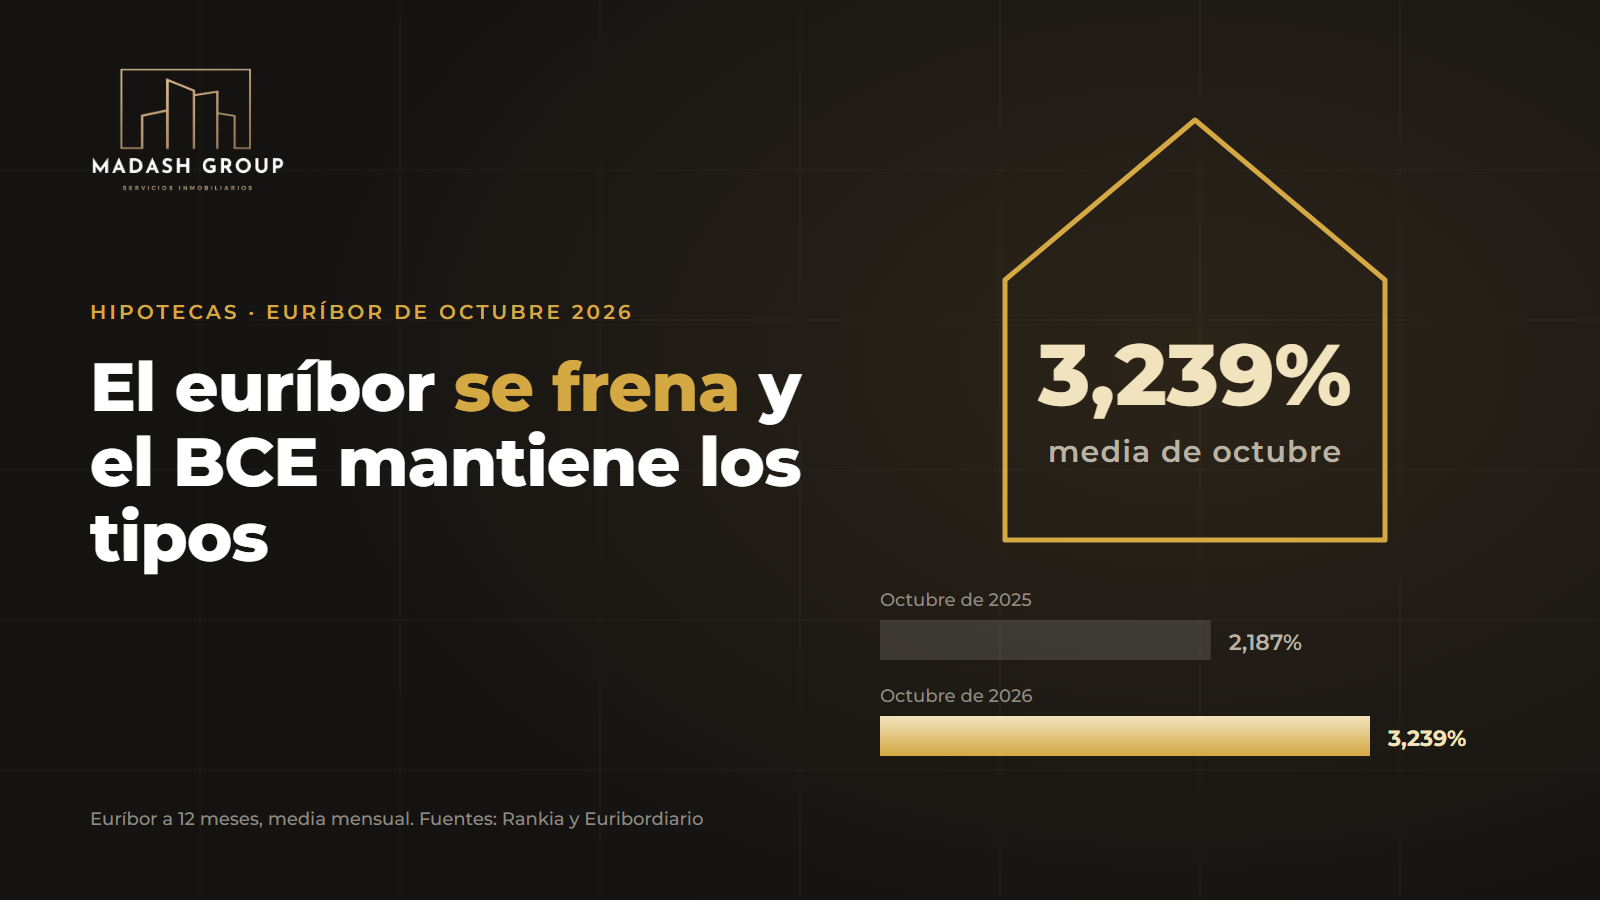
The 12-month Euribor, the benchmark for most variable-rate mortgages in Spain, closed October 2026 with an average of 3.239%. That is slightly below September (3.247%) and the first monthly fall since June. In the same month, the European Central Bank (ECB) decided to hold interest rates, although it has not ruled out raising them again. If you have a mortgage or are thinking of buying or selling in Reus or Tarragona, this is what you need to know.
October's Euribor in figures
- October average: 3.239%, calculated over 22 sessions.
- Compared with September: 0.008 points lower (3.247%), after three consecutive monthly rises.
- Compared with October 2025: just over one point higher (2.187%).
It is a pause, not a change of direction: the index ended the month above its average, at 3.306% on 30 October, and remains at levels not seen since 2024.
What happens to your repayments
If your variable mortgage is reviewed once a year and the review is due now, the rise is still significant, because it is compared with the Euribor of twelve months ago. As a rough example, on a €150,000 loan over 25 years with a margin of Euribor + 1%, the monthly payment would go from about €726 to about €812: around €86 more, just over €1,000 a year.
This is our own simplified calculation; the real figure depends on the outstanding capital, the remaining term and the margin in each contract. For those reviewed monthly, October leaves the payment practically the same as in September. Fixed-rate mortgages do not change.
The ECB holds rates
At its meeting on 29 October, the ECB left its three official rates unchanged: 2.50% for the deposit facility, 2.65% for the main refinancing operations and 2.90% for the marginal lending facility. It had raised them in September.
In its statement, the ECB warns that rising energy prices are an upside risk to inflation and a downside risk to growth, and repeats that it will decide meeting by meeting, based on the data. According to Rankia, after the meeting the market was still pricing in a quarter-point rise in December. The next meeting is on 16 and 17 December.
What does this mean for you?
If you have a variable-rate mortgage, check when your next review is due and which month it is calculated on. If the payments are tight, it may be worth talking to your bank about switching to a fixed or mixed rate.
If you want to buy, financing is more expensive than a year ago: the average rate on new home mortgages reached 3.08% in August, as we explained when analysing the INE data for Tarragona. Arriving with a mortgage pre-approval from the bank and comparing fixed, mixed and variable rates avoids surprises.
If you want to sell, remember that what each buyer can pay depends on what the bank lends them. With more expensive mortgages, an asking price in line with the market is what shortens the time it takes to sell.
At MADASH GROUP we follow the Reus and Tarragona market closely. You can ask us for a free valuation, browse the properties for sale or message us on WhatsApp.
Sources: European Central Bank, monetary policy decisions of 29 October 2026; Rankia (2 November 2026) and Euribordiario (30 October 2026). This article is for information only and does not constitute financial advice.